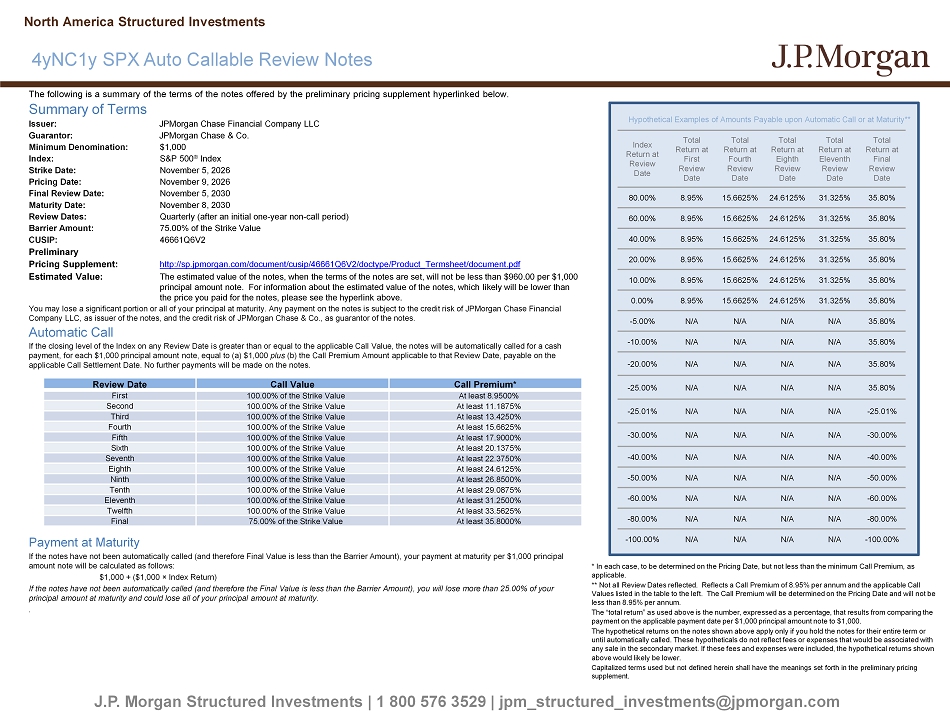
The following is a summary of the terms of the notes offered by the preliminary pricing supplement hyperlinked below. Summary of Terms Issuer: JPMorgan Chase Financial Company LLC Guarantor: JPMorgan Chase & Co. Minimum Denomination: $1,000 Index: S&P 500 ® Index Strike Date: November 5, 2026 Pricing Date: November 9, 2026 Final Review Date: November 5, 2030 Maturity Date: November 8, 2030 Review Dates: Quarterly (after an initial one - year non - call period) Barrier Amount: 75.00% of the Strike Value CUSIP: 46661Q6V2 Preliminary Pricing Supplement: http://sp.jpmorgan.com/document/cusip/46661Q6V2/doctype/Product_Termsheet/document.pdf Estimated Value: The estimated value of the notes, when the terms of the notes are set, will not be less than $960.00 per $1,000 principal amount note. For information about the estimated value of the notes, which likely will be lower than the price you paid for the notes, please see the hyperlink above. You may lose a significant portion or all of your principal at maturity. Any payment on the notes is subject to the credit ri sk of JPMorgan Chase Financial Company LLC, as issuer of the notes, and the credit risk of JPMorgan Chase & Co., as guarantor of the notes. Automatic Call If the closing level of the Index on any Review Date is greater than or equal to the applicable Call Value, the notes will be au tomatically called for a cash payment, for each $1,000 principal amount note, equal to (a) $1,000 plus (b) the Call Premium Amount applicable to that Review Date, payable on the applicable Call Settlement Date. No further payments will be made on the notes . Payment at Maturity If the notes have not been automatically called (and therefore Final Value is less than the Barrier Amount), your payment at mat urity per $1,000 principal amount note will be calculated as follows: $1,000 + ($1,000 î Index Return) If the notes have not been automatically called (and therefore the Final Value is less than the Barrier Amount), you will los e m ore than 25.00% of your principal amount at maturity and could lose all of your principal amount at maturity. . Hypothetical Examples of Amounts Payable upon Automatic Call or at Maturity ** J.P. Morgan Structured Investments | 1 800 576 3529 | jpm_structured_investments@jpmorgan.com 4yNC1y SPX Auto Callable Review Notes North America Structured Investments Total Return at Final Review Date Total Return at Eleventh Review Date Total Return at Eighth Review Date Total Return at Fourth Review Date Total Return at First Review Date Index Return at Review Date 35.80% 31.325% 24.6125% 15.6625% 8.95% 80.00% 35.80% 31.325% 24.6125% 15.6625% 8.95% 60.00% 35.80% 31.325% 24.6125% 15.6625% 8.95% 40.00% 35.80% 31.325% 24.6125% 15.6625% 8.95% 20.00% 35.80% 31.325% 24.6125% 15.6625% 8.95% 10.00% 35.80% 31.325% 24.6125% 15.6625% 8.95% 0.00% 35.80% N/A N/A N/A N/A - 5.00% 35.80% N/A N/A N/A N/A - 10.00% 35.80% N/A N/A N/A N/A - 20.00% 35.80% N/A N/A N/A N/A - 25.00% - 25.01% N/A N/A N/A N/A - 25.01% - 30.00% N/A N/A N/A N/A - 30.00% - 40.00% N/A N/A N/A N/A - 40.00% - 50.00% N/A N/A N/A N/A - 50.00% - 60.00% N/A N/A N/A N/A - 60.00% - 80.00% N/A N/A N/A N/A - 80.00% - 100.00% N/A N/A N/A N/A - 100.00% * In each case, to be determined on the Pricing Date, but not less than the minimum Call Premium, as applicable. ** Not all Review Dates reflected. Reflects a Call Premium of 8.95% per annum and the applicable Call Values listed in the table to the left. The Call Premium will be determined on the Pricing Date and will not be less than 8.95% per annum. The “total return” as used above is the number, expressed as a percentage, that results from comparing the payment on the applicable payment date per $1,000 principal amount note to $1,000. The hypothetical returns on the notes shown above apply only if you hold the notes for their entire term or until automatically called. These hypotheticals do not reflect fees or expenses that would be associated with any sale in the secondary market. If these fees and expenses were included, the hypothetical returns shown above would likely be lower . Capitalized terms used but not defined herein shall have the meanings set forth in the preliminary pricing supplement. Call Premium* Call Value Review Date At least 8.9500% 100.00% of the Strike Value First At least 11.1875% 100.00% of the Strike Value Second At least 13.4250% 100.00% of the Strike Value Third At least 15.6625% 100.00% of the Strike Value Fourth At least 17.9000% 100.00% of the Strike Value Fifth At least 20.1375% 100.00% of the Strike Value Sixth At least 22.3750% 100.00% of the Strike Value Seventh At least 24.6125% 100.00% of the Strike Value Eighth At least 26.8500% 100.00% of the Strike Value Ninth At least 29.0875% 100.00% of the Strike Value Tenth At least 31.2500% 100.00% of the Strike Value Eleventh At least 33.5625% 100.00% of the Strike Value Twelfth At least 35.8000% 75.00% of the Strike Value Final
J.P. Morgan Structured Investments | 1 800 576 3529 | jpm_structured_investments@jpmorgan.com Selected Risks • Your investment in the notes may result in a loss. The notes do not guarantee any return of principal. • Any payment on the notes is subject to the credit risks of JPMorgan Chase Financial Company LLC and JPMorgan Chase & Co. Therefore the value of the notes prior to maturity will be subject to changes in the market’s view of the creditworthiness of JPMorgan Chase Financial Company LLC or JPMorgan Chase & Co. • The appreciation potential of the notes is limited to any Call Premium Amount paid on the notes. • The benefit provided by the Barrier Amount may terminate on the final Review Date. • The automatic call feature may force a potential early exit. • No interest payments, dividend payments or voting rights. • JPMorgan Chase & Co. is currently one of the companies that make up the Index. • As a finance subsidiary, JPMorgan Chase Financial Company LLC has no independent activities and has limited assets. Selected Risks (continued) • The estimated value of the notes will be lower than the original issue price (price to public) of the notes. • The estimated value of the notes is determined by reference to an internal funding rate. • The estimated value of the notes does not represent future values and may differ from others’ estimates. • The value of the notes, which may be reflected in customer account statements, may be higher than the then - current estimated value of the notes for a limited time period. • Lack of liquidity: J.P. Morgan Securities LLC (who we refer to as JPMS) intends to offer to purchase the notes in the secondary market but is not required to do so. The price, if any, at which JPMS will be willing to purchase notes from you in the secondary market, if at all, may result in a significant loss of your principal. • Potential conflicts: We and our affiliates play a variety of roles in connection with the issuance of notes, including acting as calculation agent and hedging our obligations under the notes, and making the assumptions used to determine the pricing of the notes and the estimated value of the notes when the terms of the notes are set. It is possible that such hedging or other trading activities of J.P. Morgan or its affiliates could result in substantial returns for J.P. Morgan and its affiliates while the value of the notes declines. • The tax consequences of the notes may be uncertain. You should consult your tax adviser regarding the U.S. federal income tax consequences of an investment in the notes. Additional Information Any information relating to performance contained in these materials is illustrative and no assurance is given that any indic ati ve returns, performance or results, whether historical or hypothetical, will be achieved. These terms are subject to change, and J.P. Morgan undertakes no duty to update this information. This document shall be amended, s upe rseded and replaced in its entirety by a subsequent preliminary pricing supplement and/or pricing supplement, and the documents referred to therein. In the event any inconsistency between the information pres ent ed herein and any such preliminary pricing supplement and/or pricing supplement, such preliminary pricing supplement and/or pricing supplement shall govern. Past performance, and especially hypothetical back - tested performance, is not indicative of future results. Actual performance m ay vary significantly from past performance or any hypothetical back - tested performance. This type of information has inherent limitations and you should carefully consider these limitations before placing reliance on such information. IRS Circular 230 Disclosure: JPMorgan Chase & Co. and its affiliates do not provide tax advice. Accordingly, any discussion o f U .S. tax matters contained herein (including any attachments) is not intended or written to be used, and cannot be used, in connection with the promotion, marketing or recommendation by anyone unaffiliated with JPMorgan Cha se & Co. of any of the matters addressed herein or for the purpose of avoiding U.S. tax - related penalties. Investment suitability must be determined individually for each investor, and the financial instruments described herein may not be suitable for all investors. This information is not intended to provide and should not be relied upon as providing accounting, legal, regulatory or tax advice. Investors should consult with their own advisers as to the se matters. This material is not a product of J.P. Morgan Research Departments. Free Writing Prospectus Filed Pursuant to Rule 433, Registration Statement Nos. 333 - 293684 and 333 - 293684 - 01 North America Structured Investments 4yNC1y SPX Auto Callable Review Notes The risks identified above are not exhaustive. Please see “Risk Factors” in the prospectus supplement and the applicable prod uct supplement and underlying supplement and “Selected Risk Considerations” in the applicable preliminary pricing supplement for additional information.